


Projects
Sinphuhorm & Nam Phong,
Onshore Thailand
Horizon Net Working Interests – Sinphuhorm 7.50%;
Nam Phong 60%

Asset Overview
*MH Energy Thailand LLC (MHET) is 75% owned by Horizon and 25% owned by Matahio Energy. MHET holds a 10% interest in Sinphuhorm and an 80% interest in Nam Phong, giving Horizon effective interests of 7.5% and 60% respectively.
- Blocks E5N & EU1: Sinphuhorm gas field
JV: PTTEP (90% – Operator), EMEPK (10% – comprising Matahio (2.50%), Horizon (7.50%)
- Block E5: Nam Phong gas field
JV: EMEPK (80% – Operator – comprising Horizon (60.00%), Matahio (20.00%)), PTTEP (20%) - Acquisition of 3.9 MMboe of 2P reserves as at an effective date of 1 January 2025, with working interest of 7.5% in the Sinphuhorm gas field and 60% interest in the Nam Phong gas field, through the acquisition of 75% of the shares in EMEPK (Exxon’s Thailand holding company), with Matahio Energy acquiring the residual 25% and agreeing to manage EMEPK employees and operatorship in Nam Phong field on behalf of the Consortium *
Acquisition Highlights
- Acquired a 7.5% interest in the Sinphuhorm gas field and 60% interest in the Nam Phong gas field, onshore northeast Thailand from Exxon – both producing fields with the transaction structured to maintain Horizon as non-operator
- Effective date of 1 January 2025, with revenues earned net of costs incurred during the seven-month period from effective date to completion amounting to approximately US$10.7 million (net to Horizon) set-off against the initial cash consideration of US$30 million (net to Horizon). Contingent payments were potentially payable; however, with the relevant condition lapsing at the end of CY25, US$1.5 million of this amount will not be paid, and the remaining US$6 million (net to Horizon) remains contingent
- Transaction will enable the Company to maintain it’s current distribution strategy, while enhancing cashflows and diversifying and growing the production base
- Represents a Thailand country re-entry and establishes a low-cost platform for growth in South-East Asia, partnering with a likeminded operator (Matahio)
- Cash accretive well-understood producing assets, with 2P reserves forecast generating ungeared returns well above Horizon’s investment hurdles
- Substantially debt funded – financing structure enhances the potential to sustain or enhance distributions, with minimal impact on Horizon’s existing cash reserves on completion
- Provides further diversification of the Company’s production base by adding two more gas assets in a fourth jurisdiction
- Potential running room through life extension at both fields, infill drilling, facility upgrades and optimisation, together with numerous additional opportunities existing in both assets
Background
Blocks E5N & EU1: Sinphuhorm gas field (Horizon net 7.5%)
The onshore Sinphuhorm gas and condensate field, 500 km NNE of Bangkok, was discovered in 1983 and began production in 2006. It’s a north-south trending inversion anticline with a Permian-aged fractured carbonate (PNK) reservoir, producing dry gas with low condensate yield (~2 bbl/MMcf).
Development includes 11 wells across three pads in the central and southern areas. Pressure depletion indicates good reservoir connectivity. Northern well PH-14 is scheduled for tie-in in 2026. During June 2025, the field produced average 119 TJ/d gross sales gas (Horizon net 8.9 TJ/d). By year-end 2024, cumulative production reached 637 PJ (611 bcf) gas and 2.3 MMbbls condensate—about 63% recovery to date, with an estimated 82% recovery factor expected.
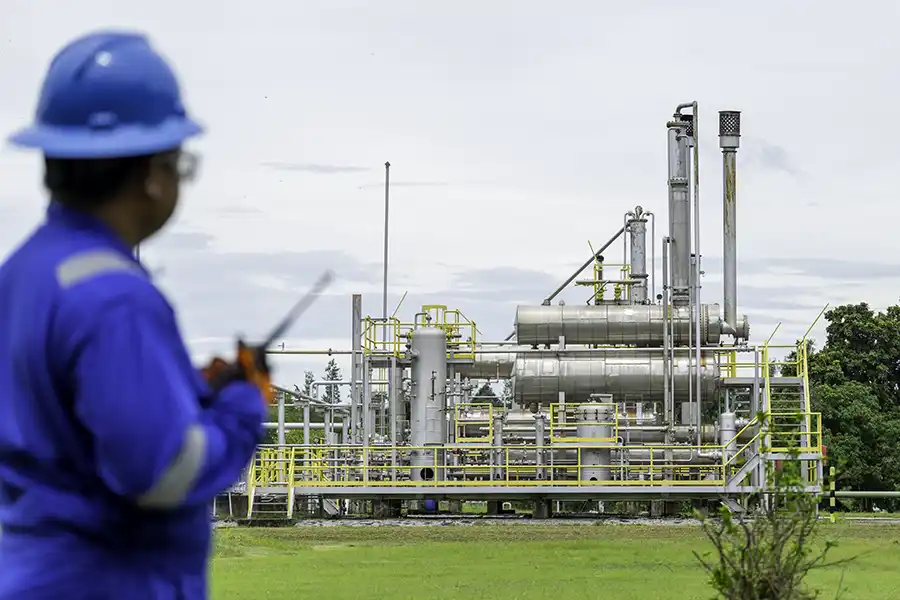
All wells tie into a central gas plant (140 MMscf/d capacity) with condensate stabilization. The plant is low-cost (~US$2.2/boe, excl. tax/royalties). Horizon’s 7.5% share of decommissioning costs is estimated below US$2 million.
Raw gas is sent via a 64 km pipeline to the PTTEP-operated Sinphuhorm Gas Processing Plant, then to EGAT’s Nam Phong power plant. Sales are under a take-or-pay GSA with PTT, running through March 2031. Demand has exceeded 90 MMscf/d for four years, with strong outlook amid tight regional supply and high import prices. Pricing is tied to high-sulphur fuel oil. Condensate is sold to PTT under a long-term deal. A 2024 compression project boosted production.
At 31 Dec 2025 production from Sinphuhorm and Nam Phong averaged ~2,087 boepd net to Horizon. Sinphuhorm delivered average gas sales of 111.42 TJ/d (8.4 TJ/d net) and condensate sales of 210 bopd (16 bopd net), while Nam Phong averaged 5.8 TJ/d (3.5 TJ/d net) over the period. Gas sales at both fields were consistently above nominations, except for an 11‑day period in November when one Sinphuhorm booster compressor was offline for repair. Nam Phong production continued to exceed nominations through the quarter.
EPC contracts for Wellpad D and the associated flowline were awarded in early September. Contractors mobilised in November, with line pipe arriving at port in early January. PH-14 achieved first gas on 11 August 2026, approximately 50 days ahead of schedule, and was initially delivering 25–30 MMscf/d gross.
Plans are also advancing for the Q4 2026 tie‑in of PH1‑ST, following additional perforations.
Block E5: Nam Phong gas field (Horizon net 60.0%)
The onshore Nam Phong gas field, located 440 km NNE of Bangkok and 60 km south of the Sinphuhorm field, was discovered in 1981 and began production in 1990. It is a fault-bounded, N-S trending anticline formed by inversion tectonics, overlying a reactivated fault block with Permian-aged fractured carbonate (PNK) reservoir containing dry gas.
After exploration and appraisal wells in 1981–82, four development wells were drilled from 1989–91, with first gas in December 1990. Between 1997–99, three infill wells increased capacity to 132 TJ/d (130 MMscf/d) to meet contract requirements. Of the nine wells drilled, seven are producing. As a depletion drive reservoir, production has declined with pressure, an by June 2025 production was ~6.1 TJ/d, with Horizon’s net share at 3.6 TJ/d. Operating costs are low at ~US$11.7/boe (excl. tax and royalties), and Horizon’s 60% share of decommissioning costs is under US$4 million.
Gas is sent to the nearby EMEPK-operated Gas Stabilisation Unit (GSU) for dehydration, then to the adjacent PTT gas metering station. Custody transfer occurs at the GSU outlet. PTT sells the gas to EGAT, which runs the Nam Phong power plant ~3 km away. No condensate is currently produced.
Following the September JV “Produce the Limit” workshop, the Operator progressed field‑wide optimisation trials at Nam Phong. Implementation of the refined Reservoir Management Plan has delivered an estimated 7% uplift on the field’s forecast production rates, achieved without any capital expenditure. These operating improvements are now being embedded into the long‑term production strategy.
The Nam Phong Booster Gas Compressor entered service on 4 September 2026. Initial field sales were approximately 10.3 TJ/d gross, 84% above average sales prior to start-up. The project reduces backpressure, improves well deliverability and supports increased gas recovery.
Quick Links
Horizon Head Office
Level 4, 360 Kent Street
Sydney NSW 2000
T: +61 2 9332 5000
Email Alerts
Subscribe to our email alerts
If you no longer wish to receive Horizon Oil Investor News select the button below
Follow us


